What Each Option Actually Is #
Both products turn unpaid customer invoices into cash before your customer pays. They differ in what you hand over and who stays in charge.
Invoice factoring is a sale. You sell specific invoices to a factor at a discount. The factor advances a share of the invoice value, often 80% to 90%, then pays you the balance, less its fee, when your customer pays.
Invoice financing is a loan. You pledge your receivables as collateral. You still own the invoices, send them, and collect. When the customer pays, you repay the advance plus the finance charge.
The paperwork differs too. A factoring agreement transfers the invoices. A financing agreement is a secured loan. Article 9 of the Uniform Commercial Code, adopted in every state with local variations, covers both sales of receivables and loans secured by them. It governs how a claim on your receivables is created, filed, and ranked against other creditors.
Who Collects From Your Customers #
With factoring, the factor usually collects. Customers are told to pay the factor, often at a new remittance address. That takes the chasing off your desk, which is the main reason owners choose it. It also means a third party contacts your customers about money they owe you.
With invoice financing, you collect. Customers keep paying you, and you repay the lender. Some lenders ask for remittance copies or a controlled collection account, but the customer relationship stays with you.
Choose factoring if you lack the time or staff to chase slow payers. Choose financing if you want collections in your own hands.
Invoice Factoring vs Invoice Financing: What Each Costs, Side by Side #
Costs are where comparisons go wrong, so compare them on the same invoice, the same advance, and the same period.
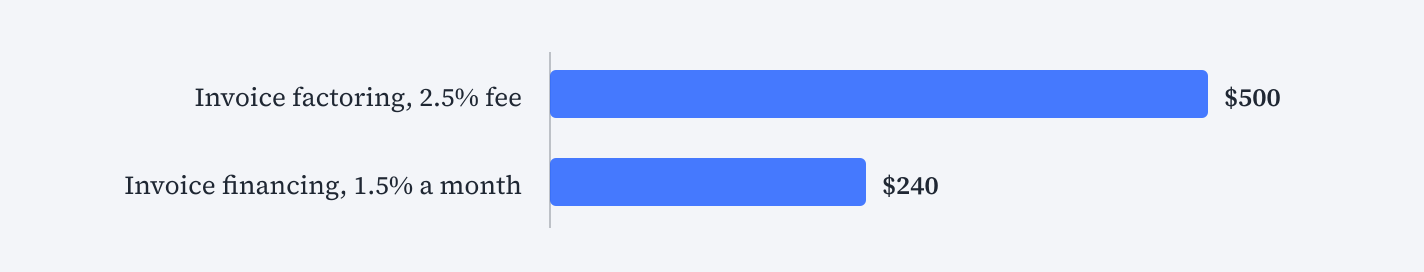
Factoring is often priced as a fee on invoice value, charged for each period the invoice stays open. For example, take a $20,000 invoice with an 80% advance ($16,000) and a 2.5% fee for 30 days. The fee is $500. Measured against the $16,000 you actually receive, that is about 3.1% for the month, or roughly 37% a year if the invoice is paid in 30 days. If the invoice stays open 60 days, the fee doubles to $1,000.
Invoice financing is usually priced as a finance charge on the amount advanced. For example, a $16,000 advance at 1.5% a month costs $240 for 30 days, or about 18% a year. That is less in dollars than the factoring fee. But you carry the collection work, the lender holds a lien on your receivables, and origination or processing fees may add to the cost.
| Option | Typical cost | Speed | What it needs |
|---|---|---|---|
| Invoice factoring | Fee on invoice value per period; for example 2.5% per 30 days on an 80% advance ≈ 37% a year on the cash advanced | Often days once the account is approved | Invoices to creditworthy customers; a sale or assignment of invoices |
| Invoice financing (receivables loan) | Finance charge on the advance; for example 1.5% a month ≈ 18% a year, before other fees | Days to a few weeks | Aging report, invoice detail, a lien on receivables |
| Bank line of credit secured by receivables | Interest on the amount drawn; often the lowest cost of these options if you qualify | Weeks, after underwriting | Business financials, tax returns, time in business |
| SBA 7(a) loans | Interest within SBA maximums plus lender fees | Weeks to months | Eligible business, documentation, often a personal guarantee |
| Merchant cash advance | Factor rate: 1.25 factor over 8 months ≈ 65–75% APR | Often within days | Recent bank statements or card sales history |
Effect on Your Books and Customer Relationships #
Factored invoices leave your receivables. Your balance sheet shows the cash received and a smaller receivables balance, and the fee is usually recorded as an expense. Financed invoices stay on your books as receivables, with the advance shown as a liability. Confirm the treatment with your accountant.
Customer contact differs as well. Factoring usually means customers receive notice and a new remittance instruction, which some take well and others do not. Invoice financing is usually invisible to customers, although some lenders verify invoices directly with them.
When Factoring Is the Right Tool #
Factoring fits when your customers are creditworthy but slow to pay, when you have no one to chase invoices, and when you need cash fast. Because the factor weighs your customers' credit more than your own history, it can work for a young business with thin financials.
It is a poor fit when your margins cannot absorb a fee charged every 30 days, when invoices are small, or when your customers would take a new remittance address badly. The longer an invoice stays open, the more the total fee grows.
When Invoice Financing or a Bank Line Is the Better Choice #
Invoice financing fits when your collections are strong, you want to keep customer contact, and you want a lower cost per dollar advanced than factoring usually offers.
A bank line of credit secured by receivables is often the cheapest and most flexible option if you qualify. You draw only what you need, repay, and draw again. The trade-off is time: banks ask for financial statements and run underwriting, so a line is a poor fit if the cash is needed this week. An SBA 7(a) loans suits larger, longer-term needs, though it also takes paperwork and time.
A merchant cash advance is not an invoice product. It is repaid from future sales, which makes it a different tool for a different problem. It also usually costs far more than any option above, so it is generally a last choice when invoices or a bank line could do the job.
How to Decide and What to Ask a Provider #
Start by listing your open invoices, their due dates, and how many days customers actually take to pay. Then price each option for that real period, not a best case.
Ask every provider for the total dollar cost, every fee, and the annualized rate in writing. Ask whether the agreement is recourse, meaning you must replace unpaid invoices, or non-recourse. Ask what happens to customer contact, what the lien covers, and how early repayment works.
How Much Does Invoice Factoring Cost Compared With Invoice Financing? #
Per dollar advanced, factoring usually costs more, because the fee pays for collections and sometimes part of the credit risk on your customers. In the example above, the same $16,000 advance costs $500 under factoring at 2.5% for 30 days and $240 under financing at 1.5% a month. The gap narrows if you would otherwise pay staff to chase invoices, and it widens the longer invoices stay open. Ask each provider for total dollars and the annualized rate in writing before you choose.
Will My Customers Know I Am Using Factoring? #
Usually, yes. With factoring, customers are told to pay the factor, often at a new address, and the factor will contact them about balances. With invoice financing, most customers never see the lender, though some lenders verify invoices directly. Ask each provider how it handles customer contact, and tell your key customers before the change so it is not a surprise.
Can I Use Invoice Financing If I Already Have a Bank Line of Credit? #
Sometimes, but check your bank's loan agreement first. Many bank lines take a lien on accounts receivable, and a second lender usually cannot claim the same invoices without the first lender's consent. Ask your bank in writing whether it allows additional financing against receivables or will release specific invoices. Factoring raises the same question, because a factor buying your invoices needs clear title.
Which Option Is Faster to Set Up? #
Factoring is often fastest once you are approved, sometimes within days, because the provider looks heavily at your customers' credit. Invoice financing can take a little longer because of lien filing and review of your receivables. A bank line of credit is usually slowest, taking weeks or longer. Speed also depends on how clean your aging report is, so ask each provider for a written timeline.
What Happens to My Invoices If a Customer Never Pays? #
It depends on the agreement. With recourse factoring, you usually must buy back or replace an unpaid invoice after a set period. Non-recourse factoring covers some credit losses, typically customer insolvency, but usually not disputes over the goods or services. With invoice financing, the invoice stays yours, so you repay the advance and fee on schedule, and the lender may pursue the receivable under its lien. Read the default and dispute terms closely before you sign.
Whether This Fits Your Receivables #
If your invoices are sound and your cash is tied up in them, factoring can be a fast fix at a real cost. If you can wait and a bank will lend against receivables, a line is usually cheaper. If you want to keep customer contact, invoice financing deserves a close look. To see what your own invoices could support, start a request and our network of funding partners will review your options with you.
Sources #
Categories, not companies. Ranges are typical for U.S. small businesses as of the update date, not offers. How this site is paid.